Published on UzonMart | Personal Finance & Money Management
Saving money is an important part of financial independence, but for many salaried individuals in India, putting money aside every month can feel challenging. Rising household expenses, rent, transportation costs, groceries, electricity bills and family responsibilities often leave little room for savings.
However, developing healthy financial habits does not always require a large monthly income.
With careful planning, realistic budgeting and consistent effort, even individuals earning a modest salary can begin building their savings.
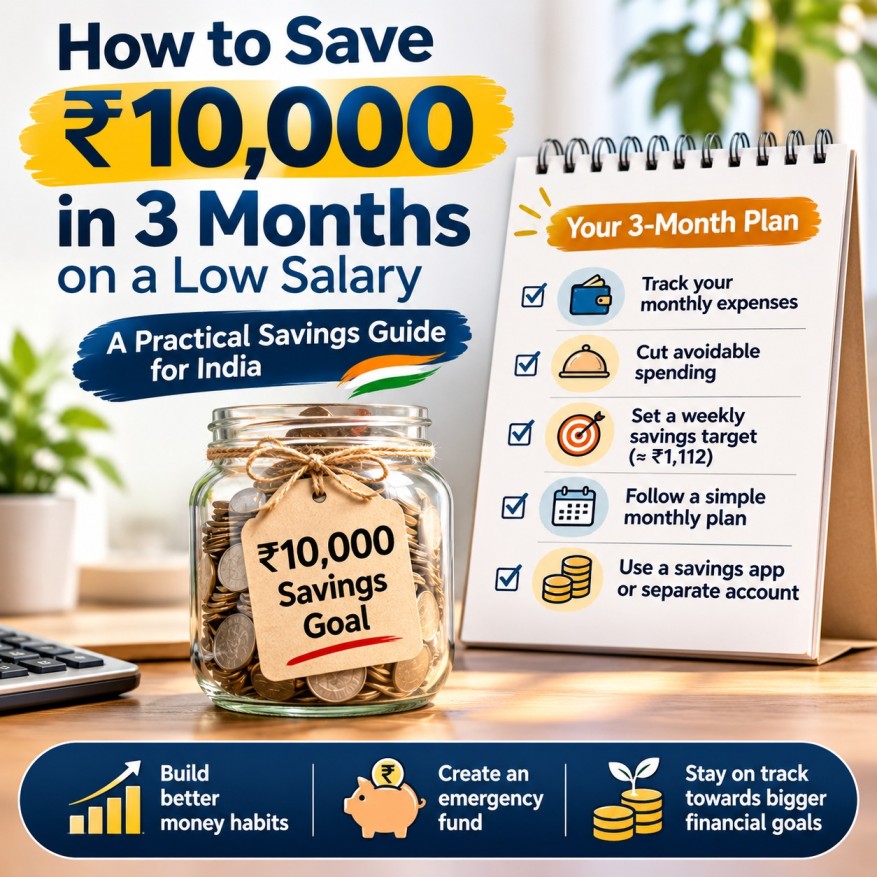
If your goal is to save ₹10,000 within three months, the first step is to understand how much you can realistically afford to set aside.
At UzonMart, we believe financial awareness helps individuals make more informed decisions about their money. Through educational resources and insights into financial services, we aim to make practical money management easier to understand.
In this guide, we explore effective savings strategies, realistic budgeting techniques and useful financial lessons. We also introduce Jora Capital, a digital lending platform that emphasises responsible credit decisions and transparency in borrowing.
Why Is Saving Money Important for Salaried Individuals?
A monthly salary provides regular income, but financial stability depends on how effectively that income is managed.
Many people focus primarily on earning more money while overlooking the importance of controlling expenses and preparing for unexpected situations.
Savings can support several important financial needs.
1. Financial Security
Having money set aside can reduce financial pressure when unexpected expenses arise, such as urgent household repairs, medical bills or temporary income interruptions.
2. Reduced Dependence on Borrowing
Savings can help cover planned purchases and smaller emergencies without automatically depending on personal loans or credit cards.
3. Better Financial Discipline
Saving regularly encourages individuals to monitor expenses, identify unnecessary spending and make thoughtful financial decisions.
4. Preparation for Future Goals
Whether you want to purchase a laptop, pay education fees, plan a family trip or build an emergency fund, savings can help you work toward these goals.
The amount saved matters, but building a sustainable habit is equally important.
How Much Should You Save to Reach ₹10,000 in Three Months?
A financial goal becomes easier to manage when divided into smaller targets.
Here is a simple breakdown of a ₹10,000 savings challenge.
| Savings Goal | Approximate Amount |
|---|---|
| Total Target | ₹10,000 |
| Duration | 3 Months |
| Monthly Savings | ₹3,334 |
| Weekly Savings | ₹770 |
| Daily Equivalent | ₹112 |
These figures are planning estimates. You do not need to deposit money every day.
For many salaried employees, transferring an affordable amount into savings immediately after receiving their salary may be more practical.
The most important consideration is whether the target fits your actual financial situation.
For example, saving ₹3,334 from a ₹15,000 salary requires setting aside approximately 22% of monthly income. This may be achievable for someone with low household expenses but unrealistic for someone supporting a family or paying substantial rent.
Your savings goal should never prevent you from meeting essential expenses or existing repayment obligations.
1. Start by Understanding Your Monthly Expenses
Before attempting to save money, you need a clear picture of where your income goes.
Many small purchases appear insignificant individually but can create substantial monthly expenses.
Consider reviewing your spending over the previous month.
Divide your expenses into three categories.
Essential Expenses
These are necessary for everyday living:
-
Rent and household contributions
-
Groceries and basic food requirements
-
Electricity and utility bills
-
Transportation to work
-
Healthcare and medicines
-
Essential family responsibilities
Lifestyle Expenses
These expenses may offer greater flexibility:
-
Food delivery
-
Entertainment subscriptions
-
Restaurant visits
-
Unplanned shopping
-
Premium mobile plans
-
Frequent online purchases
Financial Obligations
These include existing commitments such as:
-
Personal loan EMIs
-
Credit card payments
-
Education loan repayments
-
Other contractual financial obligations
Once your expenses are organised, you can identify areas where modest reductions may be possible.
UzonMart Money Tip: Track every expense for at least 30 days before deciding how much you can save. A clear spending record is more useful than guessing where your salary goes.
2. Prepare a Realistic Monthly Budget
A monthly budget acts as a financial roadmap.
It helps you decide how much money should be allocated toward essentials, discretionary purchases, repayments and savings.
Suppose an individual earns ₹20,000 per month.
An illustrative budget could look like this:
| Monthly Expense | Amount |
|---|---|
| Rent and Household Expenses | ₹6,000 |
| Groceries and Food | ₹3,500 |
| Transportation | ₹1,500 |
| Electricity, Mobile and Utilities | ₹1,200 |
| Personal Essentials | ₹2,000 |
| Emergency and Irregular Expenses | ₹1,800 |
| Monthly Savings | ₹4,000 |
| Total | ₹20,000 |
With this budget, an individual could potentially save ₹12,000 over three months.
However, this is only an example.
Actual expenses differ according to location, household size, income, family responsibilities and existing debt.
Someone living in Mumbai may have different housing and commuting costs compared with someone living in a smaller city.
Rather than following a rigid budget, build one around your actual circumstances.
3. Use the Save-First Approach
One common financial mistake is waiting until the end of the month to save whatever money remains.
By that time, unexpected purchases and everyday spending may have reduced the available balance.
A more structured approach is to set aside a predetermined amount shortly after receiving your salary.
For example:
If your monthly salary is ₹18,000 and you can comfortably save ₹2,000, transfer that amount to a separate savings account on payday.
Then manage your remaining expenses within the available balance.
This approach creates a clear distinction between money intended for savings and money available for spending.
You can also consider setting up an automatic transfer through your bank.
However, the transfer amount should leave enough money for essential bills and scheduled repayments.
4. Reduce Everyday Expenses Without Sacrificing Essentials
Saving money does not necessarily mean eliminating every enjoyable activity.
Small, consistent adjustments can make a difference over several months.
Prepare More Meals at Home
Ordering food regularly can increase monthly spending.
Preparing lunch at home on selected working days may help reduce unnecessary expenses.
Review Digital Subscriptions
Streaming services, applications and other subscriptions can quietly increase recurring costs.
Review which services you actually use and consider cancelling unnecessary subscriptions.
Plan Grocery Purchases
Preparing a shopping list before visiting a supermarket can help reduce impulse buying.
Comparing prices and purchasing suitable quantities may also support better budgeting.
Avoid Unplanned Online Shopping
Discount notifications and limited-time offers can encourage purchases that were not originally planned.
Before buying something, consider whether it is genuinely needed.
Review Mobile and Internet Plans
Check whether your current recharge or internet package matches your actual usage.
Avoid paying for features or data allowances that provide little value.
For example, reducing discretionary spending by ₹60 on 20 days each month creates a potential saving of ₹1,200 monthly.
Over three months, that could amount to ₹3,600.
5. Follow a 90-Day Savings Challenge
A three-month challenge can make saving more engaging and easier to track.
Instead of focusing on the complete ₹10,000 immediately, divide the goal into manageable stages.
Example 90-Day Savings Plan
| Month | Target Savings | Cumulative Savings |
|---|---|---|
| Month 1 | ₹2,500 | ₹2,500 |
| Month 2 | ₹3,000 | ₹5,500 |
| Month 3 | ₹4,500 | ₹10,000 |
| Total | ₹10,000 | ₹10,000 |
Month 1: Build Awareness
Begin by understanding your expenses and identifying unnecessary purchases.
Establish a budget and start saving a realistic amount.
Month 2: Improve Consistency
Continue tracking your spending.
Review subscriptions, shopping habits and recurring expenses to identify further savings opportunities.
Month 3: Strengthen Your Savings
If your financial circumstances allow, increase your savings contribution through reduced discretionary spending or additional income.
This is an illustrative challenge rather than a mandatory schedule.
If the final month's target is too high, extend the savings period instead of compromising essential expenses.
6. Explore Opportunities to Earn Additional Income
For some people, reducing expenses alone may not be enough to reach a short-term savings target.
In such situations, additional income can help.
Depending on your skills, work schedule and available resources, you might explore:
-
Freelance graphic designing
-
Content writing
-
Video editing
-
Online tutoring
-
Social media management
-
Translation services
-
Weekend part-time assignments
-
Other legitimate skill-based work
For example, earning an additional ₹1,500 per month could create ₹4,500 in extra income over three months, before any applicable costs or taxes.
If that amount is saved, it can contribute significantly toward your goal.
Avoid opportunities that demand suspicious upfront payments or promise unrealistic guaranteed earnings.
At UzonMart, we encourage readers to explore business opportunities thoughtfully, compare available services and make informed decisions before committing money.
7. Understand the Difference Between Saving and Borrowing
Saving and borrowing serve different financial purposes.
Savings involve setting aside money from existing income for future needs.
Borrowing involves receiving funds that must generally be repaid according to agreed terms, potentially including interest and fees.
A personal loan may help address a genuine financial requirement, but borrowing money simply to achieve a savings target is not a sound savings strategy.
Loan repayments can also reduce the amount available for future savings.
Before considering credit, evaluate your financial situation carefully.
Ask yourself:
-
Is the expense essential?
-
Can the purchase be postponed?
-
Can existing savings cover part of the requirement?
-
Will the repayment amount fit comfortably within my budget?
-
Do I understand the total borrowing cost?
These questions are important for responsible money management.
8. Understanding Responsible Digital Lending with Jora Capital
India's digital financial services sector has made it possible for eligible borrowers to explore loan options through mobile applications.
However, convenience should always be accompanied by an understanding of borrowing costs, repayment conditions and lender credibility.
Jora Capital is a digital lending platform focused on making the online loan application process more accessible and understandable.
The platform operates as a Lending Service Provider (LSP), helping facilitate digital loan applications through its lending partner.
According to Jora Capital's supplied platform information, its lending partner is Salora Capital Limited, an RBI-registered Non-Banking Financial Company (NBFC).
Jora Capital is not itself the direct lender.
What Should Borrowers Check Before Applying for a Digital Loan?
Annual Percentage Rate (APR)
APR helps borrowers understand the annualised cost of credit, including applicable charges accounted for in its calculation.
Processing Fees
Some loan products include processing fees and applicable taxes. These should be considered when comparing offers.
Repayment Tenure
Borrowers should understand the repayment schedule and whether it aligns with their income.
Key Fact Statement (KFS)
The KFS provides important information about loan costs and conditions. It should be reviewed before accepting an offer.
Lending Partner
Borrowers should verify which regulated financial institution is responsible for originating and servicing the loan.
Total Repayment Amount
The overall amount payable is often more useful for budgeting than looking at the loan principal alone.
Jora Capital's Published Loan Information
The information supplied for Jora Capital includes the following indicative details:
| Loan Feature | Published Information |
|---|---|
| Loan Amount | ₹1,000 to ₹50,000 |
| Repayment Tenure | 61 to 180 Days |
| Maximum APR | 36% per annum |
| Processing Fee | ₹0 to ₹1,500 plus applicable GST |
| Lending Partner | Salora Capital Limited |
| Application Mode | Digital |
These details are based on the supplied platform information and should be verified against the current official disclosures before publication or application.
Actual loan terms, eligibility and approval depend on the lender's assessment.
For additional information, visit the Jora Capital official website.
You can also explore the Jora Capital mobile application on Google Play.
Important: Borrowing should be considered only when necessary and when repayments are affordable. A loan should not be treated as a substitute for building regular savings.
9. Keep Your Savings Separate from Everyday Spending
One practical way to protect your savings is to maintain a clear separation between daily expenses and money reserved for future goals.
A dedicated savings account can help you monitor progress more easily.
For example, you could use your primary bank account for salary deposits, bills and daily spending while maintaining a separate account for your savings goal.
When selecting an account, consider minimum-balance requirements, fees, withdrawal accessibility and other applicable conditions.
For a short-term target such as three months, access to your money and preservation of capital are important considerations.
Avoid assuming that high-return investment products are suitable for money you may need soon.
10. Build an Emergency Fund for Long-Term Stability
A ₹10,000 savings challenge can be a useful starting point, but financial security requires preparation for unexpected expenses.
An emergency fund is money reserved for unforeseen situations.
Examples include urgent healthcare needs, necessary home repairs, temporary job loss or unexpected family responsibilities.
The appropriate emergency fund amount depends on your essential expenses, income stability and personal obligations.
If you have no emergency savings, it may be sensible to begin building a small financial cushion before pursuing an aggressive short-term savings target.
As your income grows, you can gradually strengthen this reserve.
Financial stability is more important than meeting a savings deadline at any cost.
11. Review Your Financial Progress Every Week
Tracking progress helps you understand whether your plan is working.
Choose a convenient day each week to review your spending and savings.
Consider checking:
-
How much money did I save this week?
-
Did I spend more than planned?
-
Which expenses could be reduced?
-
Are there upcoming bills or irregular costs?
-
Can I maintain my savings target next week?
You can use a notebook, spreadsheet or budgeting application.
If an unexpected expense interrupts your progress, adjust the plan rather than abandoning it.
Consistent financial awareness can be more valuable than following a perfect budget for only a few weeks.
Practical Savings Plan for Different Monthly Salaries
Savings capacity varies considerably across income groups.
The following table shows what a ₹3,334 monthly savings target represents as a percentage of different salaries.
| Monthly Salary | Monthly Savings Target | Approximate Salary Percentage |
|---|---|---|
| ₹12,000 | ₹3,334 | 27.8% |
| ₹15,000 | ₹3,334 | 22.2% |
| ₹18,000 | ₹3,334 | 18.5% |
| ₹20,000 | ₹3,334 | 16.7% |
| ₹25,000 | ₹3,334 | 13.3% |
| ₹30,000 | ₹3,334 | 11.1% |
These figures demonstrate why the same savings target may be easier for some individuals than others.
For someone earning ₹12,000 per month, saving nearly 28% of income may be difficult after covering basic necessities.
In that situation, a smaller monthly target or longer timeline may be more sustainable.
Common Money-Saving Mistakes to Avoid
Setting Unrealistic Targets
Saving too much too quickly can create pressure on essential household expenses.
Choose an amount you can maintain consistently.
Ignoring Existing Debt
Loan EMIs and credit card obligations should be considered before setting a savings target.
High-interest debt may need attention before aggressively increasing savings.
Relying on Uncertain Earnings
Bonuses, freelance projects and incentives are not guaranteed.
Avoid building essential financial plans around income that has not yet been received.
Overlooking Small Purchases
Repeated discretionary expenses can reduce the amount available for savings.
Review them regularly without eliminating necessary or meaningful spending.
Using Loans to Fund Savings
Borrowed money creates a repayment obligation and may involve interest and fees.
It does not represent savings generated from income.
Failing to Prepare for Emergencies
Unexpected expenses can disrupt financial plans.
Maintain some flexibility and gradually build an emergency reserve.
How UzonMart Supports Financial Awareness and Business Discovery
Financial education is not limited to understanding bank accounts, loans and investments.
It also involves knowing how to evaluate services, compare opportunities and make informed decisions.
UzonMart is a business discovery platform that helps users explore businesses, products and services across different categories.
Alongside business discovery, informative articles can help readers better understand important topics affecting everyday financial and business decisions.
By featuring educational content and information about platforms such as Jora Capital, UzonMart aims to make useful financial knowledge more accessible.
Readers interested in money management can explore practical savings strategies, understand responsible borrowing principles and discover relevant financial services.
This combination of business discovery and educational content supports a more informed approach to financial decision-making.
Explore more businesses, services and informative articles on UzonMart.
Frequently Asked Questions About Saving ₹10,000 in Three Months
1. Can I save ₹10,000 in three months with a ₹15,000 salary?
It may be possible if your essential expenses and financial obligations allow you to save approximately ₹3,334 monthly. If this amount is unaffordable, consider a smaller target or longer savings period.
2. How much money should I save every day to reach ₹10,000?
For a 90-day savings period, the average is approximately ₹112 per day. You can also save weekly or monthly instead of making daily deposits.
3. What is the best way to save money on a low income?
Begin by tracking expenses, preparing a realistic budget, reducing unnecessary spending and transferring an affordable amount into savings regularly.
4. Is it possible to save money while paying EMIs?
Yes, depending on your income and existing obligations. Essential expenses and scheduled repayments should be prioritised. If debt costs are high, reducing debt may be more appropriate than pursuing an aggressive savings target.
5. Should I follow the 50/30/20 budgeting rule?
The 50/30/20 approach can be a useful reference, but it may not suit people whose essential expenses consume most of their income. A personalised budget is often more practical.
6. Where should I keep money saved for a three-month goal?
Consider an accessible savings option that prioritises capital safety and suitable withdrawal conditions. Review fees and account requirements before choosing.
7. Can additional income help me save ₹10,000 faster?
Yes. Legitimate freelance work, tutoring or other skill-based assignments may help increase your savings capacity. Actual earnings will depend on available opportunities and individual circumstances.
8. What is Jora Capital?
Jora Capital is a digital lending platform operating as a Lending Service Provider. According to its supplied information, loans facilitated through the platform are provided by its lending partner, Salora Capital Limited, subject to eligibility and lender assessment.
9. Can I use a personal loan to complete my savings challenge?
Borrowing to meet a savings target is generally counterproductive because it creates a repayment obligation and may add interest and fees.
10. How can UzonMart help readers learn about financial services?
UzonMart provides business discovery opportunities and informative content that can help readers explore services, understand financial concepts and make more informed decisions.
Conclusion: Start Small and Build Better Financial Habits
Learning how to save ₹10,000 in three months on a low salary is about developing a practical approach to managing money.
A clear budget, regular expense tracking, thoughtful spending decisions and achievable savings goals can help individuals make steady progress toward financial stability.
The objective should not be to save money at the expense of essential needs.
Instead, focus on creating habits that can continue beyond the initial three-month challenge.
At UzonMart, we encourage readers to explore useful financial knowledge, discover relevant services and approach money management with confidence and awareness.
Platforms such as Jora Capital also highlight the importance of understanding digital lending options, borrowing costs and repayment responsibilities when credit is genuinely required.
Whether your first savings milestone is ₹1,000, ₹5,000 or ₹10,000, consistent progress can provide a foundation for stronger financial habits.
Explore UzonMart and Jora Capital
Discover Businesses and Services with UzonMart
Explore business categories, services and informative resources.
Website: https://uzonmart.com/
Learn More About Jora Capital
Explore information about digital lending and responsible borrowing.
Official Website: https://joracapital.co/
Google Play App: https://play.google.com/store/apps/details?id=com.joracapital.app&hl=en_IN
Connect with the Founders of Jora Capital
Amar Nalawade, Co-Founder: https://www.linkedin.com/in/amar-nalawade-44900b409/
Saurav Jaiswar, Co-Founder: https://www.linkedin.com/in/saurav-jaiswar-162184408/
Disclaimer: This article is published for general educational and informational purposes and does not constitute personalised financial advice or a recommendation to borrow. Budget and savings examples are illustrative. Loan eligibility, approval, interest rates, fees and repayment terms depend on the applicable lender's policies and current disclosures. Readers should independently verify lender information, review the Key Fact Statement and loan agreement, and consider their repayment capacity before applying for credit.